A newly incorporated Lahore fintech wants to become the “Uber of investing”. But reporting published today shows its internal projections have it spending Rs4,500 to acquire one customer who invests just Rs500 — a nine-to-one loss before a rupee of revenue. For a country that watched Airlift collapse in 2022 after burning over a hundred million dollars, the comparison is uncomfortable, and the questions are fair.
The ‘Uber of investing’ pitch
File photo: a young man checks his smartphone. EquiDash targets young, mobile-first users. Photo: DP Singh Bhullar (CC BY-SA 4.0).
Profit by Pakistan Today reported on 3 November 2026 that the founders of EquiDash, a recently incorporated Lahore-based fintech, want to build what they call “Uber but for financial investment” — a mobile platform connecting young, unbanked users with fractional shares and money market funds. The goal is not absurd: Pakistan has a huge unbanked population and very low retail investment, so lowering the barrier to investing addresses a real gap.
The problem, as TechX’s analysis of Profit’s reporting lays out, is the road being taken. Internal projections reviewed by Profit show EquiDash burning Rs4,500 in targeted Instagram ads and free Careem ride credits to convince one university sophomore to put Rs500 into a money market fund — a nine-to-one loss on every customer before the business earns anything.
Rs4,500 to win Rs500: the uncomfortable maths
File photo: the closing bell at the Karachi Stock Exchange. In fintech, unit economics decide who survives. Photo: Foreign and Commonwealth Office (OGL v1.0).
Unit economics are the quiet arithmetic under every pitch deck: what it costs to win a customer versus what that customer will ever generate. When the first number dwarfs the second, no vision bridges the gap. As the analysis bluntly puts it, spending Rs4,500 to generate Rs500 in invested assets does not work at any scale, in any market, under any funding conditions.
Money market funds — the product at the centre of the reported projections — earn fractions of a percent in fees. The Rs500 would need to sit untouched for years before the company recovered even part of its Rs4,500 cost, assuming the customer stays and keeps investing — all of which costs more.
These are internal projections reviewed by a publication, not audited financials, and startups iterate on acquisition strategy. But they raise the question every founder must now answer: at what customer number does this stop losing money? If the answer needs a miracle funding round, the product must change before the pitch deck does.
The Airlift parallel Pakistan remembers
File photo: a large e-commerce logistics centre. Airlift’s model collapsed under warehouse and fleet costs. Photo: CC BY-SA 4.0.
Pakistan has seen this film before. In 2021, Airlift raised $85 million in Series B — the largest round by any startup in Pakistan, the Middle East and North Africa at the time — taking total funding to $110 million at a $275 million valuation. It looked like a national triumph.
Underneath, the numbers told another story. In Q1 2022, Airlift reported $21.9 million in gross revenue but just $900,000 in net revenue — a 4 per cent margin — while burning $5.3 million in cash at the adjusted EBITDA level. In June 2022 the founders said Airlift was “remarkably close to profitability”. A planned Series C then collapsed when investors needed more than two months to wire the money. Airlift did not have two months. On 12 July 2022, it shut down permanently.
Airlift masked weak economics with marketing subsidies, warehouse networks and fleet costs that outpaced revenue in a price-sensitive market. EquiDash is a different product in a different sector — but the structure of the problem is identical: spending far more to acquire a user than that user will ever generate.
A leaner funding landscape in 2026
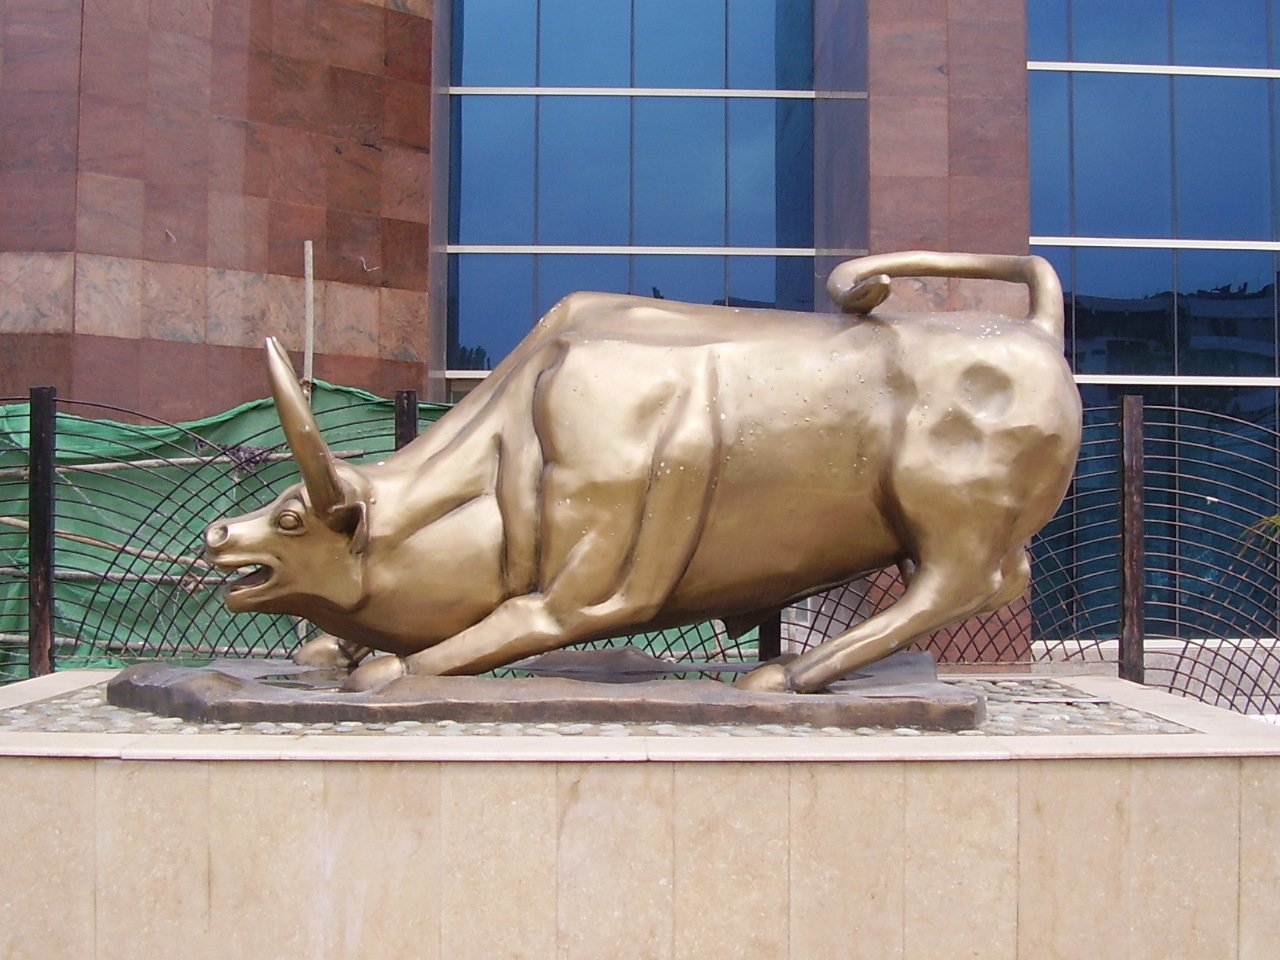
File photo: the bull statue outside the Islamabad Stock Exchange. Fintech still dominates deal flow, but investors demand revenue. Photo: Danish47 (CC BY-SA 3.0).
The context makes such burn rates dangerous. Pakistan has roughly 450 fintech firms that have collectively raised about $391 million in venture capital — but capital has tightened severely. Startups raised $133.7 million across 10 deals in 2026 so far, with $74.7 million in Q3, according to i2i Ventures. Strip out Fasset’s $68 million Series C — 91 per cent of the quarter — and startups raised roughly $6.7 million in Q3. Early-stage capital is scarce.
After equity investment collapsed nearly 90 per cent in two years to about $22.5 million in disclosed 2024 deals, founders can no longer count on the next round. The survivors share one trait: revenue independent of fundraising. PostEx survived the funding winter by being sustainable rather than spectacular; Haball raised a $52 million pre-Series A backed by real transaction volume.
Fintech still accounts for 34 per cent of Q1 2026 deal flow and has dominated every funding year. Investors still believe in the sector — as this broader look at Pakistan’s startup ecosystem shows. They just no longer believe in growth at any cost. And as TechX’s analysis of Profit’s reporting concludes, the lesson is not that ambition is wrong — it is that the core numbers have to work.
Read also: Pakistan Single Window’s digital wallet for traders and PVARA’s anti-money-laundering oversight of crypto.
Related Posts
 TechnologyApple Shares Slide as New CEO John Ternus Warns of ‘Unprecedented’ Memory Chip Costs
 TechnologyPakistan Has 100 Million WhatsApp Users Sending 12 Billion Messages a Day, PTA Chairman Tells NA Committee
 BlogSam Altman at ADIPEC 2026: AI Now “Mostly Smarter Than Top Scientists” — But the Future Must Stay Human
 TechnologyNEVO Hunter REEV 4×4: Pakistan’s First Locally Assembled Electric Truck Enters Deliveries
 TechnologyPakistan Digital Transformation Master Plan: Three-Pillar Strategy Unveiled by PDA
 TechnologyEasypaisa Reportedly Fires Around 30 Employees Over Aggregator Account Irregularities
Most Popular
 How-ToPTA Tax Calculator 2026: Check Mobile Tax on Any Phone400 views
 Pakistan NewsPIA Boeing 787 Lease Deal: What It Means for the Airline381 views
 SportsUEFA Champions League 2026-27: Format, Teams and Schedule374 views
 Canada JobsTech Jobs in Canada: Roles, Salaries, and Skills Needed355 views
 SportsBallon d’Or 2026: London Ceremony, Nominees and All-Time Records Ahead of 70th Anniversary336 views
 ShowbizWomen’s Fashion in Pakistan 2026: Trends, Brands and Style Guide333 views