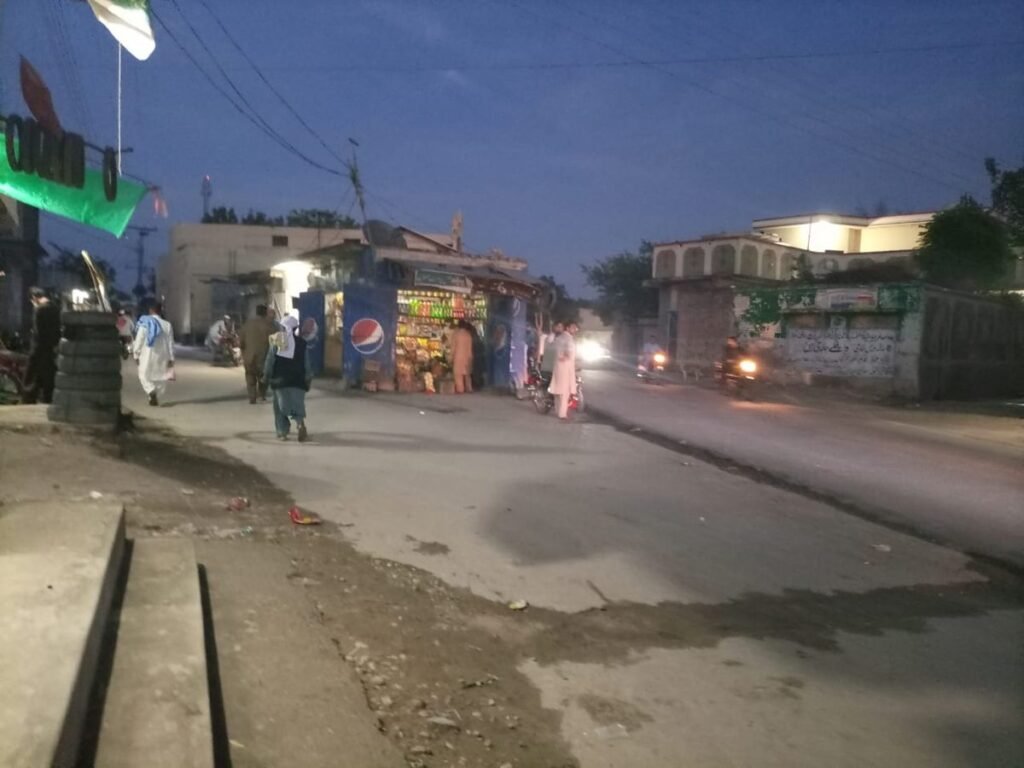
Every young shopkeeper who wants a second shutter, every farmer who needs a tube-well, and every freelancer ready to hire a first employee runs into the same wall: banks want collateral and a credit history that young people do not have. The Prime Minister’s Youth Business and Agriculture Loan Scheme — PMYB&ALS — was designed to lower that wall, offering government-subsidised loans through partner banks, starting with an interest-free tier.
This guide explains the three loan tiers exactly as published on the official PMYP loan portal, who can apply, and how the online application and bank process work. Loan decisions are always made by the bank after assessing your business plan, so treat this as a map, not a promise of approval.
The Three Loan Tiers Explained
The scheme, administered under the Prime Minister’s Youth Programme with the State Bank framework, offers three tiers:
- Tier 1: Rs. 100,000 to Rs. 500,000 at 0 percent markup — completely interest-free — repayable over up to three years. No collateral is required; a personal guarantee is the security.
- Tier 2: above Rs. 500,000 up to Rs. 1.5 million at 5 percent markup per year, with repayment of up to five to eight years depending on the loan type.
- Tier 3: above Rs. 1.5 million up to Rs. 7.5 million (Rs. 75 lakh) at 7 percent markup per year, with repayment up to eight years, including a grace period on principal for larger loans.
The bank finances most of the project cost — typically 90 percent in Tiers 1 and 2 and 80 percent in Tier 3 — and you contribute the rest as your own equity. That contribution matters: banks look far more kindly on an applicant who has some of their own money in the idea. Twenty-five percent of loans under the scheme are earmarked for women entrepreneurs, so women applicants should state their business ownership clearly in the application.
Who Can Apply?
Applicants must be Pakistani citizens holding a valid CNIC, aged 21 to 45 years. For IT and e-commerce businesses the minimum age is lower — 18 years — reflecting how young that sector starts, and some education requirements can apply there. Both new startups and existing businesses seeking expansion can apply, and farmers can apply for agriculture purposes, including crop production, livestock, dairy, poultry and fisheries, as well as machinery and development loans.
Government employees are not eligible. You should not be a defaulter of any bank, because banks check your credit record (e-CIB) during processing. For partnerships and companies, at least one partner or director must meet the age condition. There is no application fee charged by the government portal; if anyone demands money to “submit” your loan application, they are not part of this scheme.
What Can the Loan Be Used For?
Business loans can cover starting a new business, expanding an existing one, buying machinery and equipment, and working capital for day-to-day operations. Agriculture loans cover both production needs — seed, fertiliser, and seasonal inputs — and development needs such as equipment and livestock. The common thread is that the money must go into a real, identifiable business activity that your plan describes and the bank can verify. Vague plans are the single most common reason applications stall, which is why the free business-plan support from SMEDA, the Small and Medium Enterprises Development Authority, is worth using before you apply for a larger tier.
How to Apply Online, Step by Step
Applications are submitted online only, through the official portal at pmybals.pmyp.gov.pk. First, open the portal and begin with your CNIC number and its issuance date for verification. Second, complete the application form: personal details, education, the business or agriculture activity, the amount requested and the tier it falls in, and your preferred partner bank from the list on the portal. Third, submit and note the tracking information the portal gives you. Your application is forwarded to your chosen bank.
Fourth — and this is where many applicants go quiet and lose their place — respond when the bank contacts you. The bank will invite you to its branch, review your business plan and documents such as your CNIC, photographs, utility bill and, for larger loans, feasibility details, and decide the approved amount, which may be lower than what you requested. If approved, the loan is disbursed under the bank’s agreement and repayment begins on the schedule in that agreement, with the grace period applying where the tier provides one. Keep every instalment on time: a clean record on a Tier 1 loan is your strongest argument for a larger tier later.
Before You Apply: Honest Advice
Borrow only what your business cash flow can repay in a bad month, not a good one. Write the plan yourself in simple words — what you will buy, what it will earn, and how the instalment will be paid — because the bank officer will ask exactly those questions. And apply only through the official portal; screenshots of “approved loan” messages circulating on social media are a known fraud pattern.
Frequently Asked Questions
Is the Tier 1 loan really interest-free?
Yes. Tier 1 loans up to Rs. 500,000 carry 0 percent markup under the scheme; the government’s subsidy covers the cost. You repay only the principal, in instalments over up to three years.
Can a salaried government employee apply?
No. Government employees are not eligible for PMYB&ALS. The scheme is for entrepreneurs, business owners and farmers.
Can women apply, and is there a quota?
Yes. Women entrepreneurs are encouraged to apply, and 25 percent of the scheme’s lending is reserved for women-led businesses.
Where do I apply and is there a fee?
Apply free and online only at pmybals.pmyp.gov.pk. There is no paper application and no agent fee; banks process applications after the portal forwards them.
Related Posts
 Govt SchemesPM Youth Laptop Scheme: Who Could Apply, Who Could Not, and How to Check Your Status
 Govt SchemesApna Ghar Housing Loans in Pakistan 2026: What Actually Exists
 Govt SchemesNaya Pakistan Housing Programme 2026 Update: Are Registrations Open?
 Govt SchemesPunjab Kisan Card Registration 2026: How Small Farmers Can Register by SMS
 Govt SchemesPunjab Himmat Card Guide 2026: Rs. 10,500 Quarterly Stipend for Persons With Disabilities
 Govt SchemesPunjab Free Solar Panel Scheme 2026: Registration Closed — What Is Happening Now?
Most Popular
 How-ToPTA Tax Calculator 2026: Check Mobile Tax on Any Phone419 views
 Pakistan NewsPIA Boeing 787 Lease Deal: What It Means for the Airline392 views
 Canada JobsTech Jobs in Canada: Roles, Salaries, and Skills Needed389 views
 SportsUEFA Champions League 2026-27: Format, Teams and Schedule386 views
 TechnologyPM Shehbaz Sets November Deadline for Alibaba AI and Digitalisation Projects in Pakistan367 views
 ShowbizWomen’s Fashion in Pakistan 2026: Trends, Brands and Style Guide362 views


One comment